Author name: WU Content

A Family Business Owner Needs Both an Estate Plan and a Succession Plan

For family business owners, an estate plan and a succession plan often work in tandem, ensuring that both personal and business affairs transition smoothly. Your estate plan can help ensure that your assets are distributed according to your wishes and provide contingencies in the event of your death or disability before retirement. Your succession plan can pave the way for a seamless transfer of leadership upon your retirement. Here’s how they work together. Two types of succession One reason transferring a family business is so challenging is the distinction

A Family Business Owner Needs Both an Estate Plan and a Succession Plan Read More »
How Will the Changes to the SALT Deduction Affect Your Tax Planning?

The One Big Beautiful Bill Act (OBBBA) shifts the landscape for federal income tax deductions for state and local taxes (SALT), albeit temporarily. If you have high SALT expenses, the changes could significantly reduce your federal income tax liability. But it requires careful planning to maximize the benefits — and avoid potential traps that could increase your effective tax rate. A little background Less than a decade ago, eligible SALT expenses were generally 100% deductible on federal income tax returns if an individual itemized deductions.

How Will the Changes to the SALT Deduction Affect Your Tax Planning? Read More »

The New Law Includes a Game-Changer for Business Payment Reporting

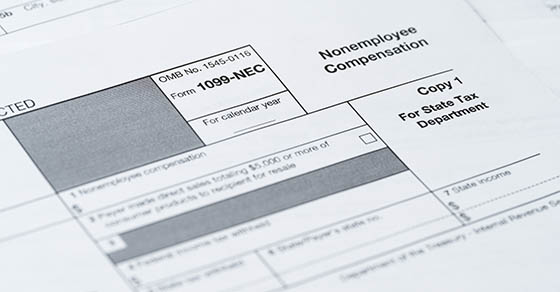
The One, Big Beautiful Bill Act (OBBBA) contains a major overhaul to an outdated IRS requirement. Beginning with payments made in 2026, the new law raises the threshold for information reporting on certain business payments from $600 to $2,000. Beginning in 2027, the threshold amount will be adjusted for inflation. The current requirement: $600 threshold For decades, the IRS has required that businesses file Form 1099-NEC (previously 1099-MISC) for payments made to independent contractors that exceed $600 in a calendar year. This threshold amount has remained unchanged since the 1950s! The same $600 threshold

The New Law Includes a Game-Changer for Business Payment Reporting Read More »

Pinched Nonprofits May Want To Free Up Board-Designated Assets

In general, nonprofits can’t use restricted assets for purposes other than those specified by the original donor. Board-designated assets (or board-designated funds) are another matter. These are unrestricted funds that have been reserved by an organization’s leadership for a special purpose or a period of time. Your board can later decide to remove designations. But you should have a board-designated assets policy to help guide you. Ready when needed Board-designated assets are subject to self-imposed limits

Pinched Nonprofits May Want To Free Up Board-Designated Assets Read More »

Scroll to Top